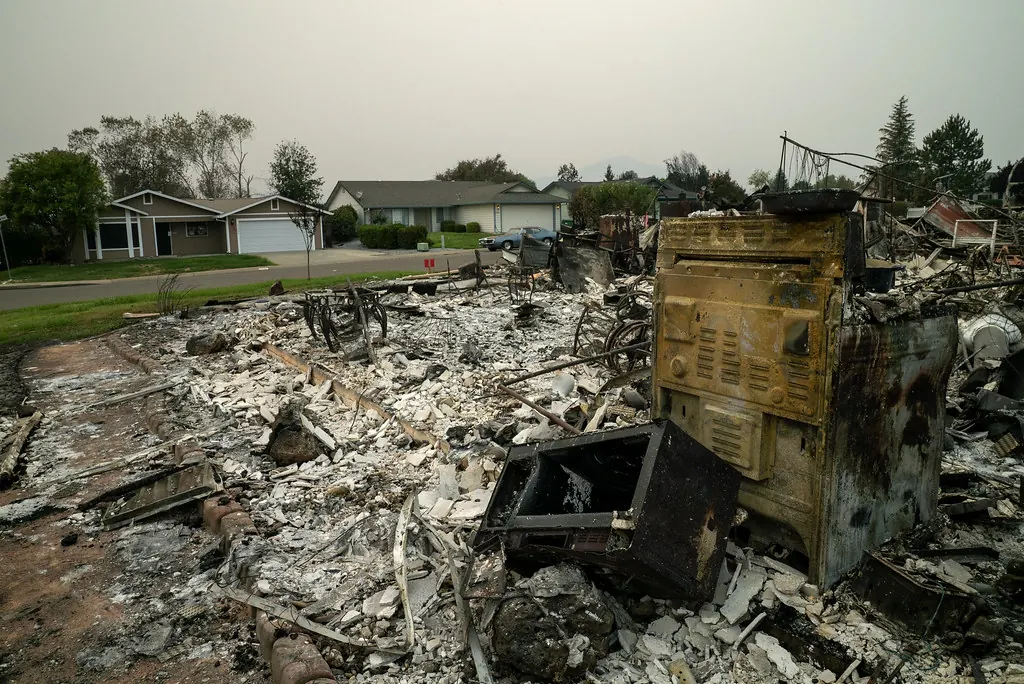
Start with the policy
Get a complete copy of your policy, including the declarations page and all endorsements. Note your dwelling, other structures, contents and living-expense limits, and whether you have extended replacement cost or ordinance-or-law coverage. Those limits shape everything that follows.
The dwelling
- Get a real rebuild estimate. After a regional fire, construction costs rise. Estimates based on normal pricing or a per-square-foot shortcut often fall short.
- Gather what the house was. Old photos, real estate listings, permits, plans and appraisals help show size, finishes and features.
- Include site work. Debris and ash removal, hazardous materials, foundation evaluation, utility reconnection, retaining walls and driveways.
- Ask about code upgrades. Rebuilding under current codes can add cost that ordinance-or-law coverage may pay.
Contents
A total-loss inventory is the hardest part of most wildfire claims. Work room by room, and use photos and videos from phones and social media, bank and card statements, and online order histories. List brand, age and quantity where you can. Our wildfire contents estimator gives an early sense of scale.
After 2020, Oregon adopted additional protections for wildfire policyholders in some situations, which may affect how detailed an inventory must be or how much time you have. Check the current rules with the Division of Financial Regulation.
Living expenses
Keep receipts for rent, mileage, meals above normal and other added costs. Rebuilds after wildfires often take much longer than first projected, and living-expense disputes are common.
Where disputes arise
- Rebuild pricing that doesn’t reflect post-disaster costs
- Depreciation on contents
- Debris removal limits
- Smoke damage to surviving structures
- How long living expenses continue
When the insurer accepts the loss but undervalues it, appraisal can resolve the amount. See our wildfire loss appraisal page.