Oregon’s wildfire reality
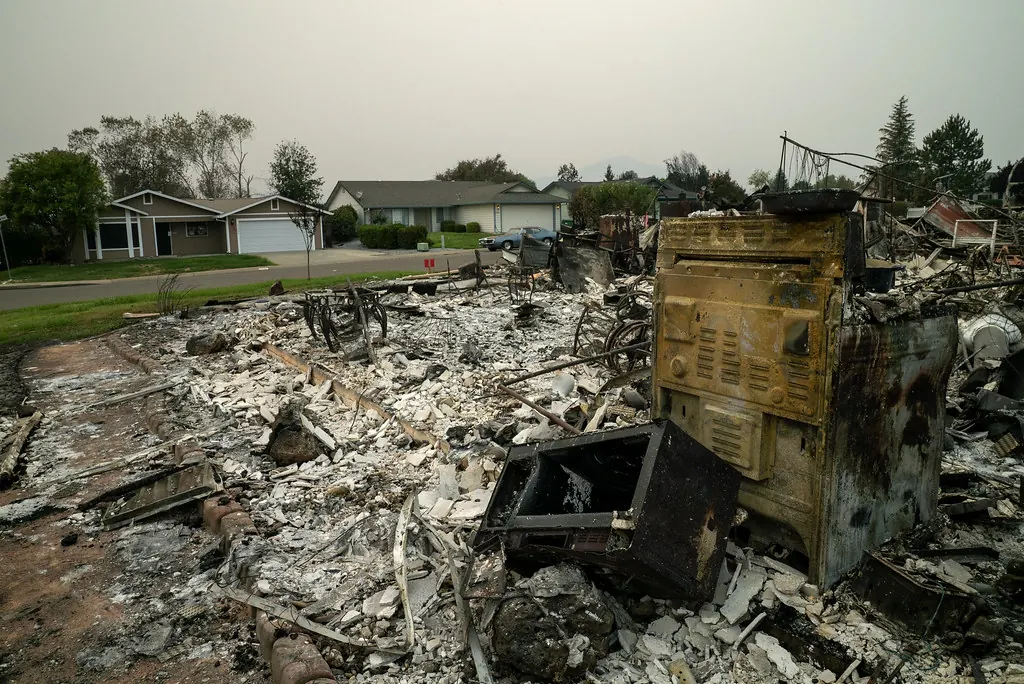
In September 2020, wind-driven fires burned across western and southern Oregon. The Almeda Fire swept through Talent and Phoenix in Jackson County. The Beachie Creek and Lionshead fires burned through Detroit, Gates and Mill City in the Santiam Canyon. The Holiday Farm Fire burned along the McKenzie River east of Springfield, and the Archie Creek, Echo Mountain and Riverside fires added to the losses. Together they destroyed several thousand homes. Fires since then have kept wildfire at the center of Oregon property insurance.
Where wildfire claims are disputed
- Rebuild cost. Construction prices after a regional disaster rise as contractors and materials become scarce. Estimates based on normal pricing often fall short.
- Debris removal and site work. Ash, hazardous materials, foundation testing, tree removal and utility reconnection.
- Code upgrades required to rebuild under current codes.
- Contents. Total-loss inventories run to thousands of items, and pricing and depreciation drive the result.
- Smoke infiltration in homes that survived, where cleaning scope is often minimized.
- Additional living expenses when the rebuild takes far longer than expected.
Oregon’s added protections
After 2020, Oregon lawmakers adopted additional protections for wildfire policyholders, including more time in some cases to collect replacement cost and to complete contents inventories after a total loss. The details depend on the policy and on whether a state of emergency was declared, so confirm what applies with the Oregon Division of Financial Regulation or an attorney.
Underinsurance is common
Many wildfire survivors discover their dwelling limit won’t cover a rebuild. Appraisal can’t raise a policy limit, but it can make sure the amount of loss is valued correctly up to that limit, including extended replacement cost coverage if your policy has it.
Questions about wildfire loss appraisal
Can appraisal increase my policy limit?
No. Appraisal values the loss, and payment is still capped by your limits. It ensures the loss is fully valued up to those limits, including any extended replacement cost coverage.
I survived the fire but my house smells of smoke. Is that a claim?
Often, yes. Smoke infiltration claims are common after Oregon wildfires, and the scope of cleaning is a frequent dispute.
Do I have to rebuild on the same lot?
Policies differ on whether you can rebuild elsewhere or buy an existing home and still receive replacement cost. Check your policy and current Oregon rules with an attorney.